Would you give a robot £100,000?
No, this isn’t the start of a new science fiction film; this is real life.
The advent of AI has led many people to consider consulting the likes of Chat GPT and Claude for advice on what to do with their money.
Research from the Financial Conduct Authority found 16% of consumers trust general-purpose AI tools for financial advice.
Nothing wrong with that, you might think – after all, these behemoths of AI have had millions of inputs and can draw on vast resources to come up with answers.
But are these answers always right?
Well, I’m afraid to say that the answer to that is “no”.
A recent report by financial technology specialist Saturn found that AI models give wrong answers to financial inquiries on average 57% of the time.
On “harder” financial questions, AI models including Chat GPT, Claude, Grok, CoPilot and Gemini made mistakes, on average, in 88% of cases.
And some AI models gave wrong answers to 99% of those more complex questions, the research found.
The problem is that AI models sound so convincing and so assured – by design – that it is easy to think they can’t be wrong.
Do that and you could end up with the financial equivalent of Michael in The US Office blindly following sat nav instructions into a lake – the Saturn research discovered that in one case, following AI financial advice could have resulted in a pension saver facing a £17,500 charge from HMRC.
Add this to the tendency for AI models to create hallucinations – in one notable case claiming that Pope Francis was still alive in 2026 – and you have a recipe for potential financial disaster.
Aside from the mistakes and other potential pitfalls of trusting too much in technology, there are other things which AI can miss when it comes to financial planning.
One of the most crucial of these is emotion – as a machine, AI cannot really tell how you feel.
It may interpret your words to think it knows what you are feeling, but not being human itself, it cannot empathise with you, put itself in your shoes and advise you from that standpoint.
A human financial adviser will be able to take into account how you feel about your finances, find out what your priorities are in life and discover your hopes and dreams.
When talking about family, an AI is likely to assume a traditional ‘nuclear’ set-up of a married couple with two or three children and make its recommendations on that.
The thing is that families in this day and age are complex.
Take mine for example – my mother and father married and divorced each other twice. My mother married for a third time to my stepfather who raised me. I have a stepbrother and stepsister as well as a sister and another sister from my father’s third marriage.
How is a computer model going to know how I feel about my family and subsequently what my priorities are when it comes to my finances?
It is only by having very human to human conversations that a financial adviser can really get under the skin of people’s lives, understand how their finances stand in relation to those lives and develop a plan which enables these often complex needs to be met.
Would you be comfortable talking to a computer about this kind of thing?
Some people may well do. However, another point to bear in mind about the likes of Chat GPT and Claude is that they are under no duty of confidentiality to you.
In fact, AI feeds on the information which it is given by people in order to grow its knowledge so the sensitive family and financial details which you are sharing apparently anonymously with your computer helper could find themselves repurposed in an answer to a complete stranger – or several thousand complete strangers. There is absolutely nothing to stop them doing so.
By contrast, regulated financial advisers in the UK have a strict duty of confidentiality to their clients. Only informed client consent or an official request from regulators such as the HMRC will allow an adviser to disclose your information to other people. Court orders, legal proceedings or financial crime and anti-money laundering obligations may also mean client information is shared.
This helps to build trust between you and your adviser that you can disclose important, sensitive information without fear of it going any further.
If your AI adviser gives you bad advice, how can you get redress?
At the moment, the simple answer is that you can’t.
AI chatbots like Gemini, Chat GPT and Claude are not authorised or regulated to give financial advice and cannot be held responsible for any financial losses incurred as a result of their guidance.
This situation has led to the Financial Conduct Authority (FCA) calling for artificial intelligence providers to introduce clearer warnings about the limitations of AI-generated financial advice – but as yet, beyond general statements such as ‘Chat GPT can make mistakes’ no such warnings are in place.
By contrast, regulated financial advice comes with a formal complaints and redress framework, including access to an independent ombudsman and a compensation scheme for eligible claims against failed firms.
Regulated financial advisers such as ours in Fairstone also have to comply with a range of rules and standards set by the FCA covering professional competence, ethical conduct, suitable personalised recommendations, transparent charges, ongoing service obligations, quality assurance and good client outcomes.
We take our responsibilities to you seriously – as we should.
All this is not to give the impression that I’m against technology.
In fact, at Fairstone we’re making increasing use of it – not to replace human interaction but to enhance it.
In the last few months, we’ve introduced an AI agent called Fairstone CoPlanner.
With client consent, this technology records client meetings with advisers, securely storing what has been discussed, and creates notes and follow-up actions from the meetings.
This means that instead of trying to listen with one ear while scribbling down notes to refer to afterwards, our advisers can concentrate 100% on what is being discussed and focus all their attention on the client.
The process also frees up some of the administrative work normally carried out by advisers after meetings, meaning that they can spend more of their time talking person to person.
One of the key things about the system is that it is human first, AI second – whatever CoPlanner produces is always reviewed by a financial adviser and that adviser remains firmly in charge of the process.
As a result, at Fairstone your advice will always be bespoke, personalised, fully regulated and resolutely human.
For regulated financial advice with a reassuringly human touch, talk to one of our advisers today.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
AI tools can help explain financial concepts and organise information, but their answers can be inaccurate, incomplete or based on assumptions that do not reflect your circumstances. Check important information against authoritative sources and consider speaking to a regulated financial adviser before making significant financial decisions.
ChatGPT is a general-purpose AI tool, not an FCA-authorised financial adviser. Its responses should not be treated as regulated personal financial advice. The regulatory position depends on the activity being carried out, not simply whether AI is involved.
Accuracy varies according to the AI model, the question asked and the complexity of the subject. AI may explain straightforward concepts correctly but can make mistakes on complex pension, investment and tax questions. Independent verification is important before acting on an answer.
AI can help with research, calculations, explanations and administrative tasks, but it cannot reliably replace all the responsibilities of a human adviser. Professional advice involves understanding personal circumstances, assessing suitability, exercising judgement and providing an accountable service.
You should be cautious about sharing bank details, account numbers, identity documents or sensitive personal information with any AI service. Data handling depends on the provider, product, settings and applicable terms. Review the relevant privacy policy and avoid sharing information that is not necessary.
You can normally complain to the advice firm first. If the complaint is not resolved, you may be able to refer it to the Financial Ombudsman Service. If an eligible advice firm has failed and cannot pay a valid claim, the Financial Services Compensation Scheme may provide compensation, subject to its rules and limits.
AI can support tasks such as preparing meeting notes, recording agreed actions and organising information. When used with appropriate consent, security measures and human oversight, it can help advisers spend more time understanding clients and less time on administration.
Financial markets give investors access to an extraordinary range of companies, industries, countries and asset classes.
Yet beneath this apparent breadth, returns can sometimes be driven by a surprisingly small number of companies, themes or borrowers.
This creates an important challenge. An investment portfolio can look well diversified on the surface while still being heavily dependent on a relatively narrow set of underlying risks.
Concentration is not necessarily a reason to avoid successful companies, popular investment themes or particular markets.
Nor does it mean that today’s largest companies are automatically overvalued or destined to underperform.
Instead, it highlights why investors need to understand what is really driving their returns, how different investments interact, and whether their portfolio is providing the diversification they expect.
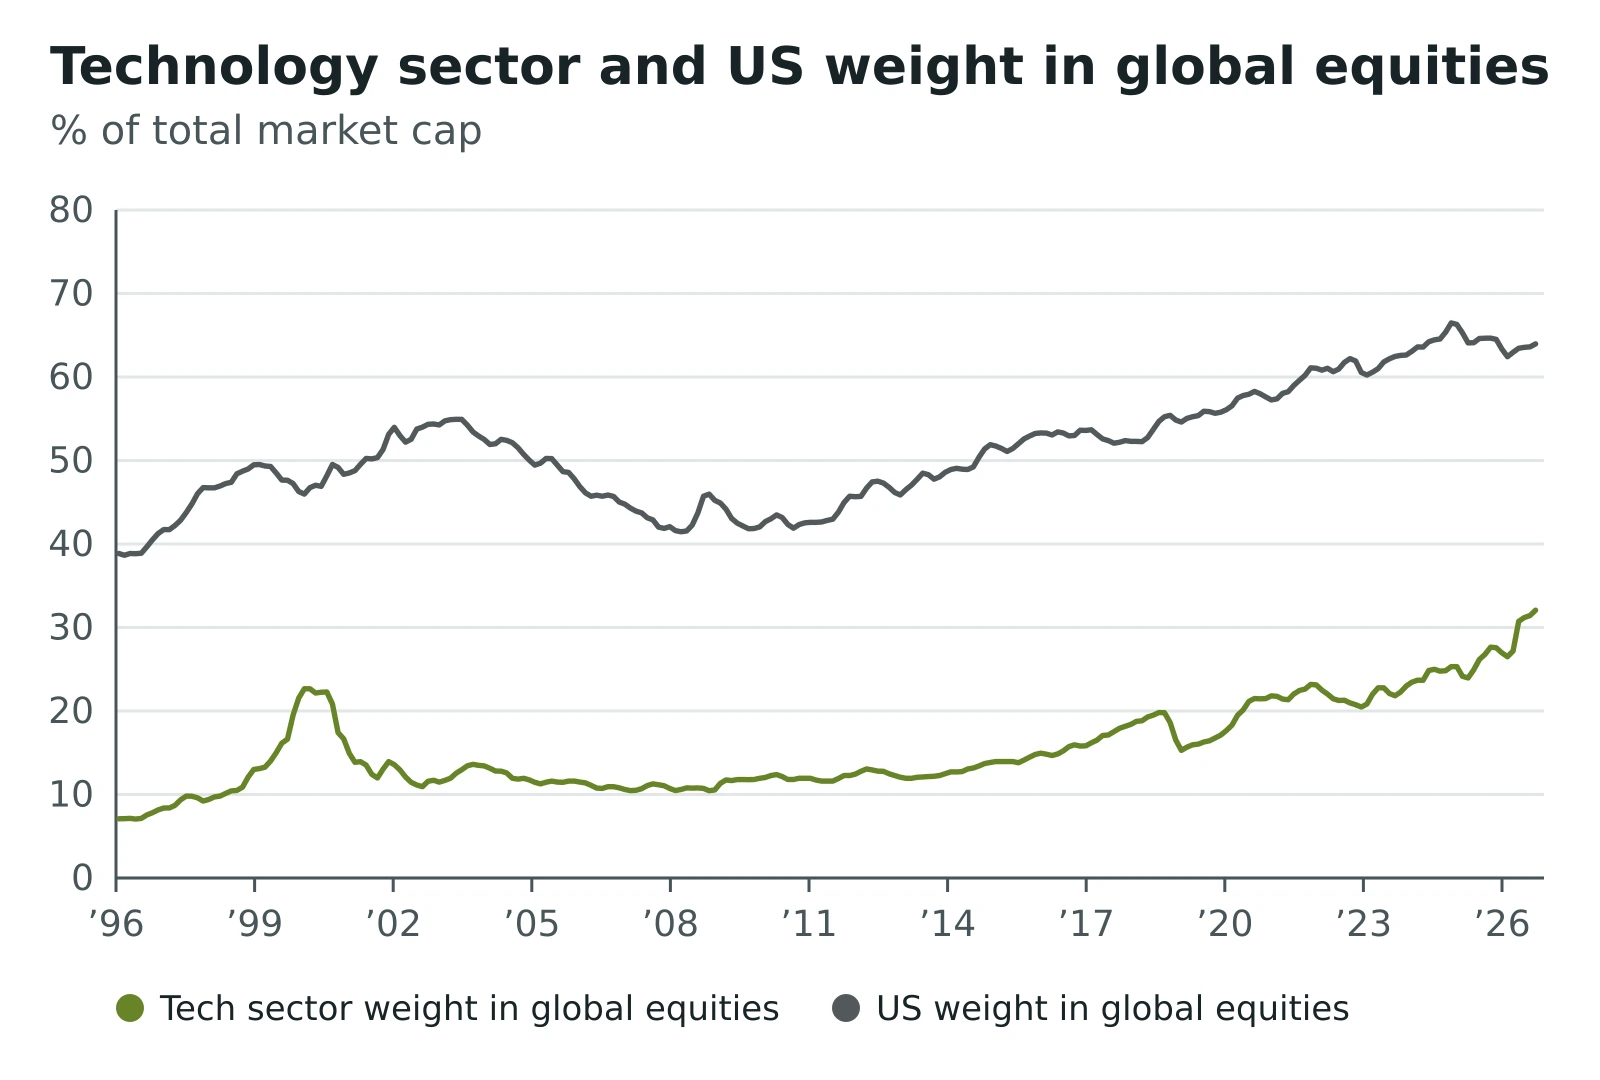
Perhaps the clearest example is the US equity market, where a relatively small group of very large technology companies has become increasingly influential.
Source: JPMorgan Asset Management
The growth of artificial intelligence (AI), cloud computing and digital infrastructure has reinforced the position of many of these businesses, with investors anticipating substantial opportunities from technological change.
This has been beneficial for investors in broad, market-capitalisation-weighted indices. As these companies have grown and their share prices have risen, they have made an increasingly important contribution to market returns.
However, the same process creates greater concentration.
Owning hundreds of companies through an index does not necessarily mean having hundreds of independent sources of return.
If a small group represents a significant share of the market, disappointing earnings, changing sentiment or a reassessment of future growth expectations can have a disproportionate effect on the wider index.
Valuations are also important. Even an excellent business can produce disappointing investment returns if its share price already reflects very optimistic expectations.
When those expectations are high, relatively small changes to the outlook can result in much larger movements in share prices.
That does not mean investors should automatically avoid the largest companies or market-capitalisation-weighted strategies.
Many leading businesses are highly profitable, possess considerable competitive advantages and generate substantial cash flows.
The important question is whether investors understand the exposure they have and how it fits alongside the rest of their portfolio.
Concentration can also arise when apparently different investments depend on the same underlying theme.
AI is a good, and well talked about, example. Investors can gain exposure through semiconductor manufacturers, cloud computing providers, software businesses, data-centre operators and companies supplying the energy and infrastructure needed to support growing computing demand.
These companies may operate in different industries and appear in different parts of an investment portfolio, but their prospects can still be closely linked.
If expectations for AI-related investment prove too optimistic, spending slows or the anticipated financial benefits take longer to emerge, the effects could extend well beyond the most obvious technology companies.
This is sometimes described as thematic concentration. A portfolio can hold many different securities while remaining unusually dependent on the success of a single economic or technological trend.
The same principle can apply to areas such as the energy transition, defence spending and emerging technologies.
These themes may offer attractive long-term opportunities, but holding them across several funds does not necessarily provide additional diversification if the underlying investments and drivers are similar.
Emerging markets have traditionally provided investors with a way to diversify equity exposure beyond developed markets, particularly the US. They offer access to different economies, currencies, industries and sources of growth.
However, looking beneath the surface now reveals a more complicated picture.
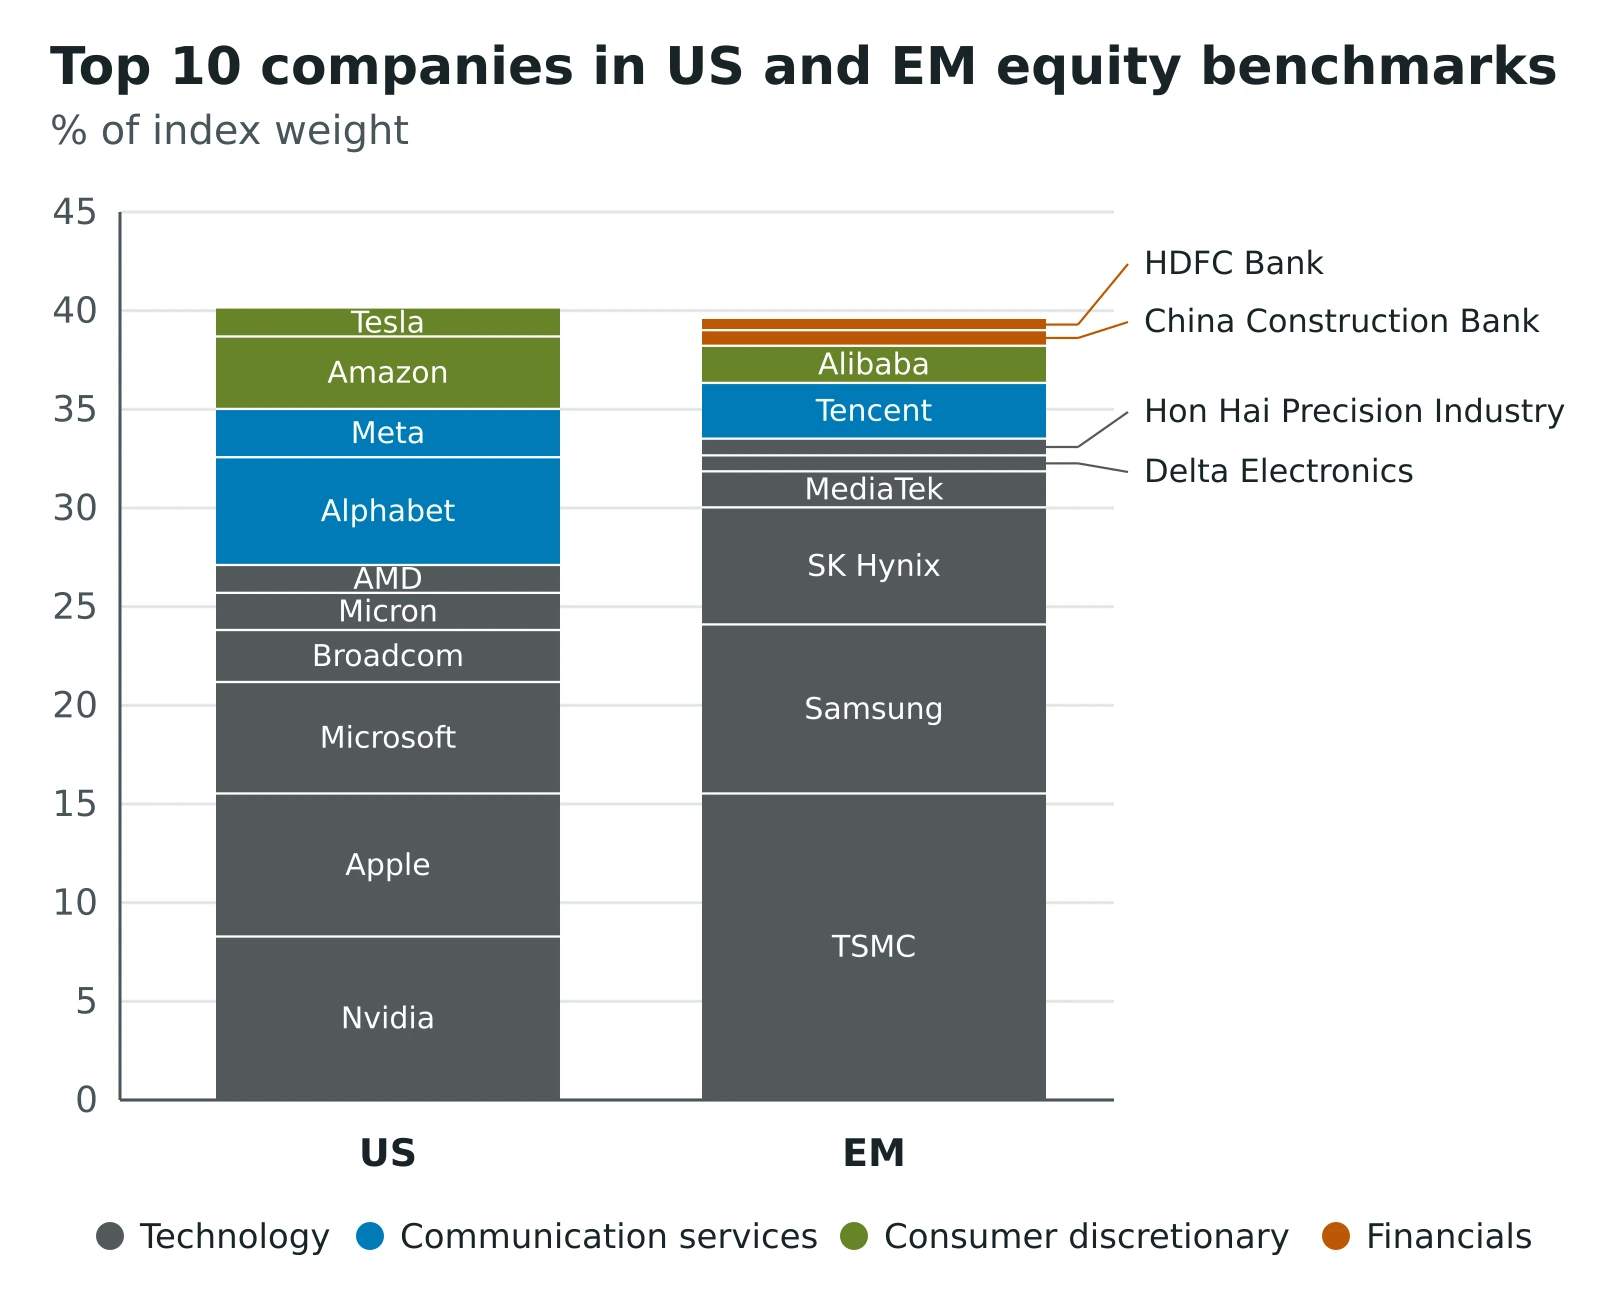
Technology businesses and companies connected to the global semiconductor and AI supply chains have become increasingly important within emerging markets.
Taiwan and South Korea, for example, are significant parts of the emerging-market investment universe, while their domestic equity markets contain several globally important technology businesses.
Source: JPMorgan Asset Management
That creates potential overlap with developed-market investments.
Semiconductor companies in Asia form a crucial part of the supply chain supporting many large US technology businesses.
An investor holding both US and emerging-market index funds may therefore have more exposure to the global technology cycle than a simple regional allocation would suggest.
This does not remove the diversification benefits of emerging markets. Their economies, currencies, domestic demand and sector mix can still behave very differently from developed markets.
But it does show why geographical diversification should not automatically be assumed to provide economic diversification.
The question is not simply where investments are located, but what ultimately drives their returns.
Similar considerations are becoming increasingly relevant within fixed income.
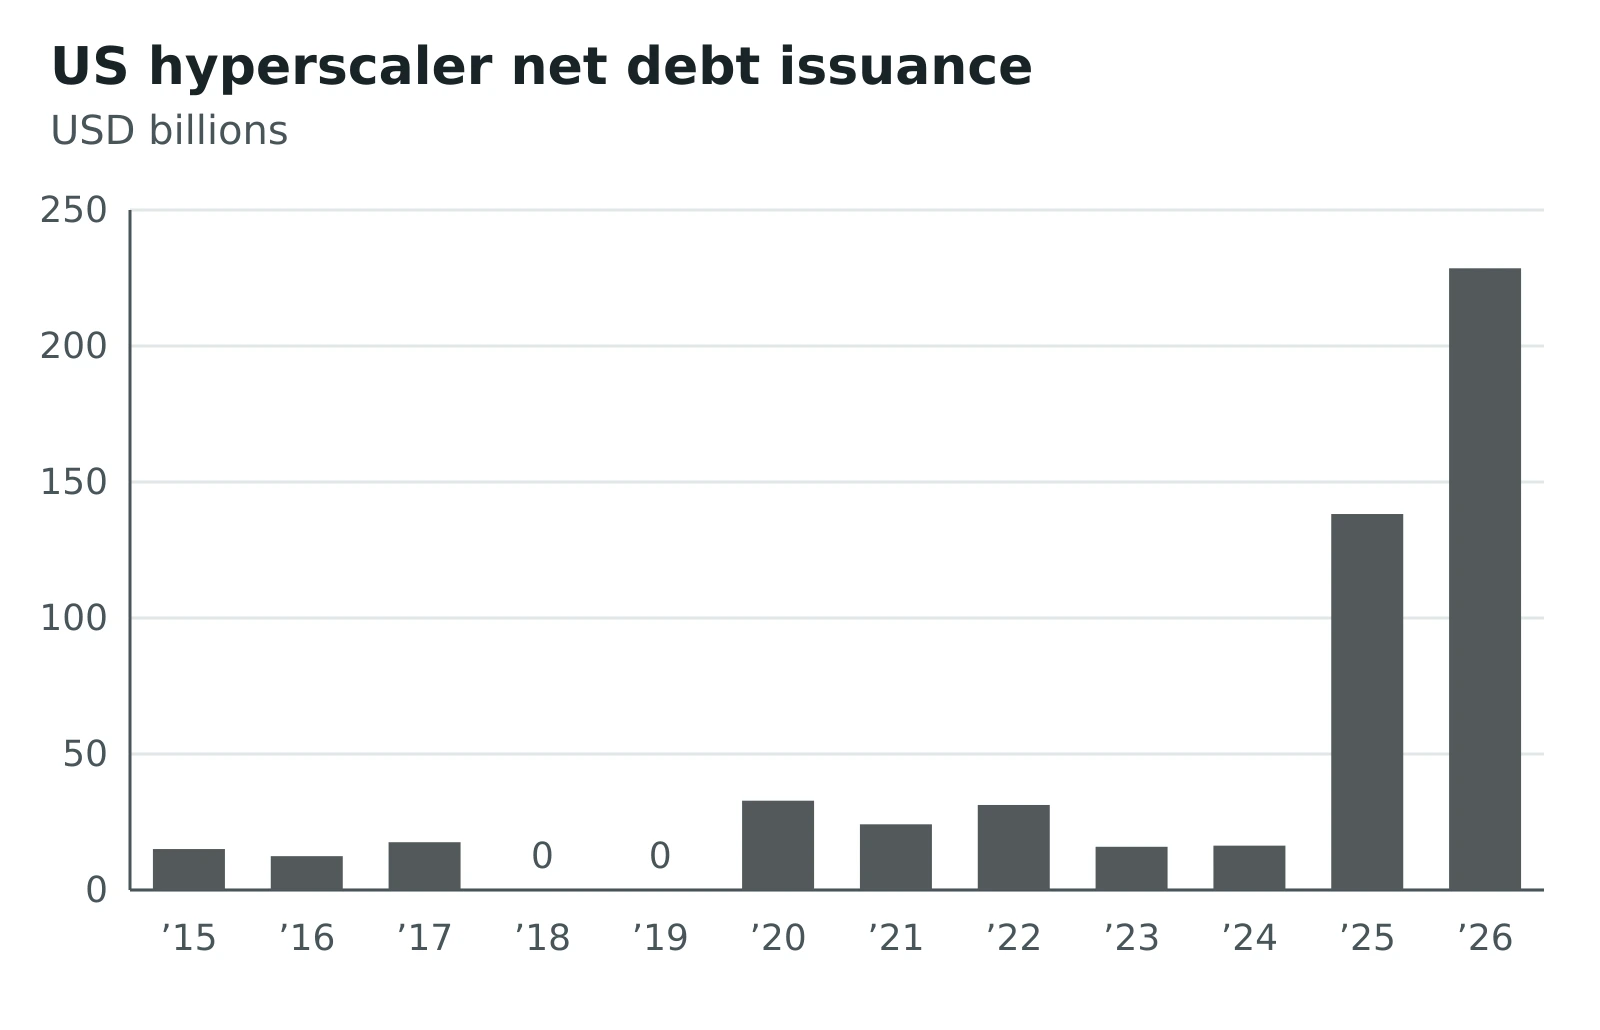
Large technology companies, including the businesses often described as hyperscalers, are investing heavily in AI infrastructure, data centres, computing capacity and cloud services.
While many have strong balance sheets and significant cash flows, the scale of this investment means debt markets now form part of their financing mix.
Source: JPMorgan Asset Management
For bond investors, this can create attractive opportunities to lend to financially strong, established companies. Corporate bonds can also broaden a fixed income portfolio beyond government debt.
However, investors may already own these same companies through their equity holdings. Buying their bonds can therefore increase total exposure to the same underlying businesses, albeit in a different form.
There is an important distinction between shares and bonds.
Shareholders participate in the potential growth of a company, whereas bondholders receive contractual interest and principal payments, subject to the issuer remaining able to meet its obligations. Bonds and equities issued by the same company can therefore behave differently.
Nevertheless, both ultimately depend on the financial health of the underlying business. If cash flows deteriorate, financing costs rise or investment plans are reassessed, both the company’s shares and bonds can come under pressure.
As before, this is not to suggest that such holdings should be avoided. Hyperscaler issuance can provide attractive, high-quality bond exposure.
Rather, the point is that a portfolio can appear well diversified across asset classes while still retaining meaningful exposure to the same underlying companies and economic drivers.
Ultimately, effective diversification is not about owning as many investments as possible.
It is about understanding what you hold, remaining focused on shifting fundamentals and combining investments that perform different roles and respond differently to changing economic and market conditions.
Holding several funds that ultimately own the same companies or depend on the same themes can create the appearance of diversification without providing all of its benefits.
The aim of a diversified portfolio is not to eliminate exposure to successful businesses or attractive long-term trends. Instead, it is to avoid becoming unnecessarily dependent on any single company, theme, region or economic outcome.
That means looking beyond fund names and asset-class labels to understand the underlying exposures within a portfolio.
What is expected to provide growth?
What is there to generate income?
Which investments could offer resilience when equity markets struggle?
And are supposedly different investments actually relying on the same underlying factors?
A well-diversified portfolio will not avoid every market downturn, and not every investment will perform well at the same time. In fact, that is partly the point. Investments that respond differently to changing conditions can help reduce the impact of weakness in any one area.
As financial markets become increasingly interconnected, diversification requires investors to look beneath the surface. The number of investments held matters less than the variety of risks and sources of return they represent.
That remains one of the most important principles in building portfolios capable of navigating an uncertain investment environment.
If you’re unsure how concentrated your portfolio is or whether it’s appropriate for your circumstances, talk to a financial adviser.
They can help you understand your current exposure and consider whether it remains aligned with your goals.
Get in touch with an adviser today to find out more.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
Investment concentration risk is the risk of a portfolio becoming too dependent on a small number of companies, sectors, regions or economic trends. If those investments perform poorly, the impact on the overall portfolio may be greater than an investor expects.
Diversification spreads investments across assets with different sources of risk and return. It can reduce the impact of poor performance in any one area, although it cannot eliminate investment risk or guarantee positive returns.
Yes, if multiple investments create excessive exposure to the same companies, sectors or market drivers. The number of holdings matters less than how those holdings behave and the risks they share.
Review the underlying holdings of your funds, including their largest companies, sector allocations, geographic exposure and asset classes. Look for investments that repeatedly hold the same companies or rely on similar economic trends.
Global funds can broaden exposure across countries and markets, but they may still allocate a substantial proportion to the largest US companies. Investors should consider the underlying sector and company exposures as well as geographic allocation.
Yes. Shares and bonds have different characteristics, but both depend to some extent on the financial health of the issuing company. Holding both may increase exposure to that business, even when the portfolio appears diversified across asset classes.
A financial adviser can assess how your investments fit together, identify potential overlap and help you consider diversification in the context of your goals, investment time horizon and attitude to risk.
I came across a rather striking statistic the other day.
Apparently, seven out of ten parents admit that they avoid talking to their teenage children about money.
More than a quarter (28%) do so because they don’t want to worry their kids, while 22% believe teenagers already have enough to focus on, according to a survey commissioned by savings and investment firm M&G.
It isn’t just parents who find talking about money problematic.
Recent research from Opinium found that 26% of people in long-term relationships (lasting two or more years) manage their lives together but not their finances.
And if that wasn’t bad enough, Co-op Legal Services found that one in three married people aged over 65 hide money from their spouse with more than one in ten having £50,000 or more stashed away on the quiet.
So while money talks, it seems we don’t talk about money.
The ironic thing is that staying silent about money in many ways can actually cost you money, not to mention the damage it can do to relationships.
And conversely, bringing the issue out of the shadows and into the light can bring multiple financial and emotional benefits.
This doesn’t mean that every conversation around the dinner table should go into the minutae of exchange traded funds or offshore bonds.
But talking things through with clarity and purpose – and taking action early as a result – can literally bring dividends.
I’ll give you an example.
Let’s say your first grandchild has been born. You want to make sure that when you are no longer here, they are provided for.
Instead of holding on to your money – and potentially letting the taxman enjoy an Inheritance Tax windfall – talk to your son or daughter about opening a child’s pension for your grandchild.
You can contribute up to £2,880 a year into that pension and, providing that doesn’t affect your day to day income, it will be free from Inheritance Tax.
What’s more, assuming you’re a basic rate taxpayer, the contributions will attract 20% tax relief from the Government so your £2,880 a year becomes £3,456 a year.
Continue that until your grandchild is 18 and that’s over £60,000.
Assuming the pension fund grows by an average of 6% a year, by the time your grandchild is 57, that pension will be worth over £1m.
Just think: a million-pound pension, all because you talked with your family about money.
Being open and upfront about finance can also be educational.
Let’s take the situation referred to at the start of this column.
What better way to introduce the topic of money to your children at an early age and talk about some of its essential features than to get them actively involved?
By opening a Junior ISA and sharing its progress with your children, you can educate them on the difference between saving and investing and how financial decisions may affect outcomes over time.
By the time they reach 18, they will hopefully have learned about what money can do for you (and what it can’t) and will be able to make sensible decisions on how they want to use their nest egg.
This isn’t about setting aside vast sums of money. The watchwords here are “early, little and often” – and it’s surprising how that builds up over time.
In my own case, the government of the day helped to give my kids a head start.
My daughters were born at a time when the Government gave every child a £250 voucher to invest in a Child Trust Fund (CTF).
We took advantage of this and invested £25 a month each for both daughters in CTFs.
Fast forward some 20-plus years and they now each have enough for a deposit on a house.
Talking more openly about money is also set to be even more important.
With the introduction of Inheritance Tax on unused pensions from April 2027, keeping mum about how much you plan to pass on to your family could leave them saddled with a substantial bill and a lot of complicated paperwork at a stressful and emotional time.
Having a family discussion could help to head off a lot of these issues – and give you and your family much greater peace of mind.
A financial adviser can help you to transform discussions into action and advise on the best path for you and your family.
However, one of the great things about having a financial adviser is that they can also act as a catalyst to have those conversations in the first place.
Having been in this business for over 25 years, I know that many people tell their financial adviser things they don’t even tell their own family.
The presence of an outside observer who possesses the expertise but doesn’t have the emotional ties is invaluable and often makes people open up.
A financial adviser who knows your wishes and who has worked on your financial plan will help you to facilitate those crucial conversations with family – and can also help the next generation to get a good financial start in life.
So if you’re finding it tricky to talk to your family about money, talk to an adviser.
It could be one of the most crucial conversations you ever have.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
Open conversations about money can help families make better financial decisions, understand each other’s wishes and plan ahead for issues such as inheritance, pensions, savings and investments.
Start with simple, age-appropriate conversations about saving, spending and investing. Involving children in a Junior ISA or another savings or investment plan can help them understand how money can grow over time.
Practical experience can be a useful starting point. Showing children how regular contributions to a savings or investment account grow over time can help them understand concepts such as compound growth, investment risk and the difference between saving and investing.
Yes. A grandparent can contribute to a child’s pension, subject to the relevant pension rules and allowances. Personal contributions of up to £2,880 a year can currently receive 20% tax relief, potentially making the contribution £3,600 gross.
Potentially. Gifts can have different Inheritance Tax implications depending on the circumstances, including whether they are considered normal expenditure out of income or fall within other gifting exemptions. Anyone considering gifts as part of an estate plan should take professional advice.
A Junior ISA is a tax-efficient savings or investment account for children. Money invested in a Junior ISA belongs to the child and can generally be accessed when they reach 18.
Talking about inheritance plans in advance can help family members understand what is intended, identify potential tax issues and reduce confusion and disagreements at an already difficult time. This can be particularly important as the tax treatment of pensions and estates changes.
A financial adviser can help families understand their options around pensions, investments, savings, gifting, Inheritance Tax and estate planning. They can also provide an impartial setting that makes difficult conversations about money easier to have.
Generally, the earlier you start, the more opportunity there is for regular contributions and investment growth to compound over time. Even relatively small amounts can become significant over several decades, although investment returns are not guaranteed.
There is no universal amount. The appropriate level depends on your own financial circumstances, objectives and whether giving money away could affect your future financial security. Professional advice can help you balance helping the next generation with maintaining your own financial resilience.
When looking through their portfolios, some investors are surprised by how much of their money is invested overseas, and how little is invested here in the UK.
For many years, overseas investments were something of an optional extra, a satellite around a UK core.
That has changed dramatically, and today they typically make up the bulk of most clients’ investments.
In this article we look at how that balance has shifted over the past few decades, the benefits and risks of investing overseas, and why it makes professional guidance more valuable than ever.
The UK remains one of the world’s major financial centres, but its stock market is a relatively small part of the global picture.
At the end of August 2026, UK companies made up around 3.1% of the MSCI All Country World Index, a widely used benchmark for global shares.
US companies accounted for around 63.6% and Japan 5.1%, while Taiwan, at 3.3%, is now larger than the UK.
| Market | Approx share of global equities |
|---|---|
| US | 63.6% |
| Japan | 5.1% |
| Taiwan | 3.3% |
| UK | 3.1% |
To put that in perspective, a single US company, Nvidia, now carries a larger weight in the global index than the entire UK stock market.
Despite this, most UK-based diversified portfolios still hold more in UK shares than the UK’s share of global markets would suggest. This is known as “home bias”.
It can be sensible, not least because it keeps more of your money in the currency you spend, but it has become less pronounced over time.
Even so, the majority of the shares in a typical modern portfolio are now listed overseas, and bond holdings increasingly include government and company debt from around the world.
It was not always this way.
In the late 1980s, global stock markets looked very different.
Japan’s stock market was roughly as large as America’s in global indices, and at its 1989 peak made up around 45% of the MSCI World Index of developed markets.
The UK accounted for around 10%, and markets such as China, India, Taiwan and South Korea were not included at all.
Today the US makes up nearly two-thirds of the global index, Japan around 5% and the UK around 3%.
Investors’ portfolios have followed the same path.
In 1997, UK pension funds held more than half of their assets in UK shares.
By 2021, according to research by the think tank New Financial, that figure had fallen to just 6%.
Over a longer period, the share of the UK stock market owned by UK individuals and institutions fell from 96% in 1981 to 42% in 2022.
Several forces have been driving this shift:
More recently, policymakers have stepped up efforts to encourage more investment back into UK companies. For now, however, a global approach remains the norm.
Many of the world’s most innovative and profitable businesses simply are not available on the London Stock Exchange.
Investing globally lets a portfolio own leading companies in areas such as:
Different economies move through different cycles, respond differently to interest rates and are exposed to different sectors.
Spreading investments across regions reduces dependence on the fortunes of any one country, including our own.
Emerging markets, such as India and other parts of Asia, benefit from younger populations, a growing middle class and rising productivity.
These are powerful long-term trends that are hard to capture through UK-listed companies alone, offering access to different sources of economic and corporate growth.
Global diversification does not automatically mean a portfolio is well diversified.
The rise of the “Magnificent Seven” (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla) means that a large slice of global stock market value now rests on a handful of companies.
As of 18 September 2026, these seven companies make up around 34% of the US S&P 500 index, compared with around 12% a decade earlier, and roughly a fifth of the global index.
Their growth has been remarkable, but concentration works both ways: in 2022 the group fell by roughly twice as much as the wider US market.
Japan, which dominated global indices in 1989, is a reminder that market leadership does not last for ever.
Some markets, especially in the emerging world, carry greater uncertainty around government policy, corporate governance and investor protections.
Trade tensions and tariffs can also affect companies with international supply chains.
When you invest overseas, unless the currency is hedged, you are also taking a position on exchange rates.
Suppose a US share rises 10% in dollar terms, but the pound strengthens by 10% against the dollar over the same period. The gain measured in sterling could be largely eliminated.
However, if the situation is reversed, a 10% share rise in dollar terms with a 10% weakening of the pound gives a UK investor substantial gains.
In 2022, sterling’s sharp fall against the dollar cushioned UK investors from some of the losses in US markets.
Currency hedging can reduce the effect of exchange rate fluctuations, but it comes at a cost and is not always desirable.
Overseas bond holdings are often hedged back to sterling, because currency swings can easily overwhelm the relatively modest returns bonds provide.
Equities are more often left unhedged, since currency movements tend to matter less over long periods and can add a useful layer of diversification.
Investing across the world, in thousands of companies and multiple currencies, adds real complexity.
That is where professional management can really help you meet your investment goals.
Assessing fund managers and companies in unfamiliar markets, with different accounting standards and governance cultures, requires specialist resources and experience.
Deciding how much to hold in the US, and in its largest technology companies, is a deliberate judgement rather than something to leave to the index by default.
Whether, when and how much to hedge depends on the asset class, market conditions and your own objectives.
Overseas investments can bring withholding taxes, dealing costs and other frictions that you need to manage efficiently.
Global conditions change quickly. Portfolios need regular review to make sure the balance between UK and overseas assets still suits your goals and attitude to risk.
There is no single ‘magic number’ or percentage of your portfolio which you should invest overseas.
Appropriate allocation will always come down to individual circumstances and will depend on a number of factors including:
The shift overseas reflects how the world economy has changed with the UK now a relatively small part of global equity markets.
Global investing provides access to companies, industries and economies unavailable through a UK-only portfolio.
However, overseas investing introduces additional risks, particularly currency and concentration risk.
And as with any investment, a portfolio including overseas investments has to be constructed in a way that reflects your objectives and circumstances.
If you’re unsure how much of your portfolio is invested overseas, or whether its balance of UK and international investments is appropriate for your circumstances, talk to a financial adviser.
They can help you understand your current exposure and consider whether it remains aligned with your goals.
Get in touch with an adviser today to find out more.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
Because the UK represents only a small proportion of global equity markets. Investing internationally can give UK investors access to companies, sectors and economies that are less represented in the UK market, while potentially reducing reliance on the performance of a single country.
The main potential benefits include greater diversification, access to a wider range of companies and industries, exposure to different economies and access to growth opportunities outside the UK.
However, overseas investments also introduce additional risks, including currency, political and regulatory risks.
Overseas investments can be affected by currency movements, political and regulatory changes, different accounting standards, market conditions and geopolitical events. Global portfolios can also become concentrated in particular countries, sectors or companies.
Home bias is the tendency for investors to hold a larger proportion of investments in their domestic market than its share of the global investment market would suggest. A UK investor who holds significantly more UK shares than the UK’s global market weighting is an example of home bias.
Currency movements can increase or reduce the return a UK investor receives from an overseas investment. If the pound strengthens against the currency of the investment, the sterling value of the investment can fall relative to its value in the foreign currency. A weaker pound can have the opposite effect.
There is no single ‘yes’ or ‘no’ answer. Currency hedging can reduce the effect of exchange-rate movements but introduces costs and does not necessarily suit every investment. The approach can also differ between asset classes; for example, currency hedging is commonly considered differently for bonds and equities.
There is no universal percentage that is appropriate for every investor. The appropriate allocation depends on factors including objectives, investment timeframe, attitude to risk, capacity for loss and the other assets already held.
Many modern pension portfolios use globally diversified funds, meaning they invest according to the size and opportunities of global markets rather than focusing primarily on UK companies. The UK’s relatively small share of global equity markets means this can result in substantial overseas exposure.
When people think about investing, they often focus on potential returns.
However, every investment involves some degree of risk.
Understanding that risk, and ensuring it matches your personal circumstances and financial goals, is one of the most important steps in building a successful long-term investment strategy.
In simple terms, investment risk is the possibility that an investment does not perform as expected, or that its value falls.
In some circumstances, investors may receive back less than they originally invested.
While this can sound daunting, risk is not something to be feared. Instead, it is something to be understood, managed and aligned with your objectives.
Generally speaking, investments that offer the potential for higher returns tend to involve higher levels of risk.
Cash savings, for example, are usually lower risk because their value is stable, but they may struggle to keep pace with inflation over time.
Investments in shares, property or other growth assets have historically delivered higher long-term returns, but their value can rise and fall significantly in the shorter term.
The key is finding the right balance between risk and reward for your individual circumstances.
This is where professional financial advice can add significant value.
While risk can never be eliminated entirely, it can be managed.
One of the most effective tools available to investors is diversification.
Rather than relying on a single company, sector or region, a diversified portfolio spreads investments across different asset classes, geographical areas and investment styles.
This approach helps reduce the impact of any one investment performing poorly.
Professional investment managers also continuously monitor portfolios, assess economic conditions and review asset allocations to ensure portfolios remain aligned with their intended risk levels.
Strategic asset allocation, diversification and ongoing portfolio oversight can all help investors stay on track while managing the ups and downs that naturally occur in financial markets.
Risk is not static. The level of risk that may be appropriate at one stage of life may be unsuitable at another.
For example, someone in their 30s saving for retirement may have a long investment horizon and be comfortable accepting more short-term volatility in pursuit of long-term growth.
By contrast, someone approaching retirement may place greater emphasis on preserving capital and generating a reliable income.
This is why advisers look at several factors when assessing suitability, including a client’s attitude to risk, financial objectives, investment knowledge and experience, and capacity for loss.
In other words, how would you feel if markets fell, and how much impact could such a fall have on your financial plans?
Many investment solutions use risk scales to help investors understand the expected level of volatility within a portfolio.
For example, risk ratings often range from 1 to 10, with lower numbers typically representing more cautious portfolios and higher numbers representing greater exposure to growth assets such as equities.
A lower-risk portfolio may hold a greater proportion of cash and bonds, aiming to deliver more stable returns with less fluctuation in value.
Higher-risk portfolios typically hold more equities and other growth-oriented investments, which can experience larger short-term movements but may offer greater long-term growth potential.
Importantly, a higher-risk portfolio is not necessarily “better” or “worse” than a lower-risk one.
The most suitable risk level is the one that aligns with your goals, timescale and personal circumstances.
Successful investing is not about avoiding risk altogether.
It is about understanding the risks you are taking, ensuring they are appropriate for your circumstances, and maintaining a disciplined approach through changing market conditions.
With the right advice, a well-diversified portfolio and regular reviews, risk becomes something that can be managed effectively, helping to keep you on track towards your long-term financial goals.
A financial adviser can explain the levels of risk involved in investments and work with you to assess which investments are most suitable for your goals, your attitude to risk and your circumstances.
To explore investments further, get in touch with an adviser today.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
Investment risk is the possibility that an investment will perform differently from expected, including falling in value or producing a lower return than anticipated. In some circumstances, investors can receive back less than they originally invested.
The appropriate level of investment risk depends on factors including your financial goals, investment timeframe, financial circumstances, attitude to risk, knowledge and experience, and capacity for loss. There is no single level of risk that is suitable for everyone.
Investment portfolios are often described as lower, medium or higher risk, although the terminology and risk scales used by investment providers vary. Lower-risk portfolios generally have greater exposure to cash and bonds, while higher-risk portfolios tend to have greater exposure to equities and other growth assets.
Attitude to risk describes how comfortable you are with investment uncertainty and potential losses. Capacity for loss describes how much financial loss you could afford to sustain without significantly affecting your financial plans or standard of living.
Higher-risk investments generally offer greater potential for long-term returns, but this is not guaranteed. Higher risk also means greater potential for losses and larger fluctuations in value.
Yes. Your appropriate level of investment risk can change as your financial circumstances, goals, investment timeframe and attitude to risk change.
Diversification across different asset classes, geographical regions and investments can help reduce the impact of any individual investment performing poorly. Matching your portfolio to your timeframe and regularly reviewing it can also help manage risk.
Cash is generally less volatile than investments such as shares, but it is not completely free of risk. Inflation can reduce the purchasing power of cash over time, particularly when savings rates are below inflation.
As retirement approaches, investors may have less time to recover from significant market falls. The appropriate approach depends on individual circumstances, including when the money will be needed, income requirements and capacity for loss.
Financial advice can help you understand how much investment risk may be appropriate for your circumstances and how that risk fits within your wider financial plan. An adviser can also review whether your portfolio remains suitable as your circumstances change.
There are many reasons why people choose to consult a financial adviser.
To help plan for their retirement; to see how they can maximise the money they put aside; to secure their legacy and pass on wealth to the next generation.
But there’s one reason that’s not talked about enough.
And that’s to feel better about themselves and their life.
The very best financial advice doesn’t just give you a pounds and pence output – it can genuinely transform your life.
You may think I’m exaggerating for effect, but I have seen it happen with my own eyes, as have many of our advisers at Fairstone.
To take an example, one client came in to see one of our advisers in a state of great anxiety.
Their workplace was undergoing a major restructure and their job was under threat of redundancy.
Naturally, the client was worried about how they would cope financially if they were to lose their job.
However, after the adviser sat down with the client and went through their finances and the plans they had put in place over the years, it was clear that not only could the client cope if they lost their job, they could actually afford to stop work altogether.
The sheer relief on the client’s face at the burden and worry that had been taken off their shoulders was quite something to behold, our adviser told me.
In another case, one of our advisers took a client on quite a retirement journey.
Before he’d first talked to our adviser, the client had assumed he’d have to work till State Pension age – 67 for him – before he could afford to retire.
With the benefit of some initial advice, 67 turned to potentially 65 – two years of additional time in retirement.
The client continued to take our advice, adjusting his plan in accordance with changes in his working life, to the point where, following some cashflow modelling exercises, it turned out that he could retire as early as 59.
The client had been handed potentially up to eight extra years choosing how he wanted to spend his time rather than having to do what his employer wanted. Add it up and that’s over 2,000 extra days of freedom to enjoy.
While it is sensible to caveat these examples by saying that investment values can go down as well as up and a model is not a guaranteed outcome, they are nevertheless life-changing conversations for the people involved.
Every adviser I’ve ever met since I started working in the industry in 1993 has got similar real-life examples of the positive impact they have on their clients.
It’s one of the main reasons why they do their job and it shows that financial advice is about so much more than figures on a spreadsheet: it’s about people’s everyday lives and how they can be changed for the better.
Done well, financial advice can turn a dream into reality and give you peace of mind and a feeling of genuine freedom.
Even the process of sitting down with an expert adviser, talking through your hopes and fears and looking clearly and closely at your finances, can make you feel better.
In fact, financial advice in many ways is financial therapy.
When you build a bond of trust with your adviser, you can tell them things which you might not tell anyone else – maybe not even yourself – and you get to share your dreams and unburden some of your worries.
Good advisers offer valuable unbiased external perspectives – they often see things about your life which you may be too busy or too involved to see and are often the catalyst for the changes that are needed.
Because the advice is personalised rather than off the shelf, you get to have a one-off plan which is unique to you and which has the flexibility to change as you do.
This means that you can take control of your life rather than just going along with things. Advice enables you to make positive choices about you and your loved ones’ lives instead of just accepting whatever comes to you.
You may have a burning desire to learn scuba diving in Bali or just want to spend more time at home spoiling your grandchildren – or maybe you want to do both.
What you need is to get advice to turn that dream into a plan and then make that plan a reality.
For expert professional advice on how to turn your life dreams into a practical plan, get in touch with one of our advisers.
| Match me to an adviser | Subscribe to receive updates |
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
If you’ve followed the financial news in recent weeks, you’ll likely have seen the headlines about a string of IPOs – Initial Public Offerings, also known as flotations.
But what does this rash of IPOs mean for investing, particularly for investors focused on long-term growth?
In June, SpaceX completed the largest stock market flotation in history, raising roughly $85 billion and debuting on the Nasdaq at a valuation comfortably above $1.7 trillion.
The shares jumped on their first day of trading, pushing the company’s value past $2 trillion, although it has since fallen to around $1.9 trillion as of the middle of July.
SpaceX may be just the beginning.
The two best-known names in artificial intelligence – Anthropic (the maker of the Claude models) and OpenAI (ChatGPT) – have both quietly filed the early paperwork for their own stock market listings.
Anthropic moved first in early June, hot on the heels of a funding round that valued it at close to $1 trillion; OpenAI followed within days.
We may be looking at three of the most closely watched companies in technology arriving on public markets within months of one another. This is something we haven’t seen since the dot-com era.
But what does this all actually mean for your portfolio?
Behind these headlines sits a trend that we have been following for many years.
A generation ago, a fast-growing company would generally “go public” – selling shares on a stock exchange – relatively early in its life, often while it was still quite small.
Listing was one of the main ways to raise serious money that was needed to grow, and ordinary investors could buy in while the business was still finding its feet.
That has now largely changed.
There is now an enormous pool of private capital available, money from private equity and venture funds, sovereign wealth funds and large institutions, that allows companies to raise tens of billions without ever troubling the stock market.
SpaceX, founded in 2002 and not listing until 2026, is just the latest, and largest, example of that.
Anthropic and OpenAI have each raised sums privately that would have been unthinkable just a few years ago. Anthropic alone closed a $65 billion funding round shortly before filing to go public.
The practical consequence is that by the time these businesses finally do list, much of their dramatic early growth has now already happened – and been captured by private investors.
Companies that once arrived on the market as small, fast-growing minnows now tend to arrive as fully grown giants, already valued in the hundreds of billions or even trillions.
There’s a second feature of these headline names that deserves attention.
Rapid growth and healthy profits are not always the same thing – and in many of these cases, the two have yet to meet.
SpaceX, for all its scale, reported a loss of close to $5 billion in 2025 as it poured money into satellites, rockets and artificial intelligence.
The picture in AI (Anthropic & OpenAI) is similar: these are businesses growing their revenues at extraordinary speed, but spending vast sums to do so, as the cost of building and running cutting-edge AI models can still outstrip the income those models generate. OpenAI, by its own projections, does not expect to be self-funding for some years yet.
None of this means these aren’t remarkable companies. It does mean their valuations rest heavily on expectations of profits far in the future, rather than profits today.
That makes their share prices (when and if they list on stock markets) more sensitive to changing sentiment and potentially more volatile.
Even among professional analysts there’s sharp disagreement. Some see SpaceX as wildly overvalued, while others argue you must judge it over a long-term horizon, with levels of growth that will more than justify the price of shares today.
So where does this leave a sensible long-term investor?
It would be a mistake to conclude that exciting, fast-growing companies have no place in a portfolio.
They can be a valuable source of long-term returns. The key is how you own them and how to appropriately size these positions.
At Fairstone, our model portfolios are deliberately built around diversification, quality and the long term.
We absolutely do seek exposure to some high-growth businesses, but always as one component of a very well-balanced portfolio, sized appropriately to your risk level and your tolerance for volatility along the way.
The aim is to capture the upside of innovation without letting any single bet dominate your financial future.
As I mentioned earlier, companies staying private for longer is a theme that we have been following for some time, and where suitable, we can find ways to invest in these private companies – should we want to.
As an example, our Nova and Multi-Instrument MPS ranges already held exposure to SpaceX while it was still a private company, as well as Anthropic while it is still private.
We hold these positions through Scottish Mortgage – a closed-ended fund which has a suitable structure to invest in these types of businesses, through a well-resourced team that has a great track record in this type of investing.
This means some of our clients participated in part of that growth journey without ever having to gamble on the timing or the valuation of the eventual flotation.
But again, the key really is that this position is held as a part of a very well diversified portfolio that is built for the long-term.
Alongside our actively managed ranges, we also offer a range of passive investing options, including Fairstone Pure Passive, which holds index-tracking funds such as the HSBC American Index and the Vanguard FTSE Developed World ex-UK Equity Index.
These trackers do exactly what their name suggests: they aim to mirror a well-known stock market index as closely as possible, holding positions in companies based on the size of the company.
When a company such as SpaceX joins a major index, every fund tracking that index is obliged to go out and buy the shares automatically.
SpaceX has already been confirmed for entry into the Nasdaq-100 and the Russell 1000, although interestingly, the S&P 500 – the most widely followed benchmark of all – declined to relax its rules and has kept SpaceX out for now, in part because the company is not yet consistently profitable.
However, most major indexes are what is known as “free-float adjusted”, meaning a company is included according to the value of the shares actually available to trade, rather than its full headline valuation.
Because so few of SpaceX’s shares are currently in public hands, it will initially carry only a relatively modest weighting in these indices, despite being one of the largest companies in the world on paper.
The point to keep in mind is that as more of its shares are gradually released over time, that weighting can climb – and trackers will quietly keep buying more of it.
Blockbuster listings make for great reading, and they genuinely do signal interesting shifts in the economy. But they are events, not strategies to focus too much on.
The investors who do best over time are rarely the ones chasing the latest debut at its moment of maximum excitement – they’re the ones who stay invested, stay diversified, and give their portfolios the years they need to compound.
Exciting companies can absolutely play their part, but they work best as carefully measured ingredients in a balanced plan rather than the whole recipe.
That long-term discipline of owning quality, diversifying risk, and matching every portfolio to the investor behind it, remains at the heart of everything we manage on your behalf.
An expert financial adviser can help you to decide on an investment plan that takes into account your circumstances and your approach to investment risk.
They can also help you to stay focused on your financial goals rather than reacting to short-term headlines or the latest investment trend.
Get in touch with an adviser today to find out more.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
An Initial Public Offering (IPO) is when a private company lists its shares on a public stock exchange, allowing investors to buy and sell ownership in the business.
They can be, but newly listed companies often experience greater price volatility. Long-term investors typically benefit most when IPO exposure forms part of a diversified investment portfolio rather than a concentrated holding.
Many fast-growing businesses now have access to significant private funding from venture capital, private equity and institutional investors, allowing them to delay public listings until they are much larger.
Large technology companies often attract valuations based on expectations of future earnings and growth rather than current profitability. This can result in higher share price volatility if market expectations change.
Index-tracking funds add newly listed companies once they are included in the benchmark index they follow. The weighting is usually based on the company’s free-float market capitalisation rather than its total valuation.
In some cases, professional investment managers can gain exposure to private companies through specialist investment trusts or private market funds. These opportunities are generally not available through traditional retail investing.
Diversification helps reduce the impact of any single investment performing poorly. Holding IPOs alongside established companies, bonds and other assets can improve a portfolio’s overall risk profile.
The Government has announced that, from April 2027, a 22% charge will apply to interest earned on cash held within non-cash Individual Savings Accounts (ISAs), such as Stocks & Shares ISAs and Innovative Finance ISAs.
This change follows ongoing calls from ISA providers and investors for greater clarity on how cash held within these types of accounts would be treated for tax purposes.
This also comes after last November’s Budget, which confirmed a reduction to £12,000 in the annual tax-free Cash ISA allowance for those under age 65 from next April.
The annual stocks and shares ISA allowance will remain at £20,000.
As a nation, the UK population invests less than other developed countries, and our personal wealth is suffering as a result.
In the UK, only 23% of people have invested in the stock market. In the US, it’s almost two thirds.
The Government hopes these changes will encourage more people to invest rather than keep cash in savings.
While the value of investments can fall as well as rise, over the long term, investments have generally delivered stronger returns than cash, which can lose value over time due to inflation.
It’s completely understandable to feel unsure about investing, with many people viewing cash as a ‘safe’ option.
However, over time, the effects of inflation can reduce the spending power of money held in cash.
With so many investment options available, it’s easy to feel uncertain about where to start.
This is where seeking professional advice can really help.
A financial adviser will take the time to understand your individual circumstances, as well as your financial and personal goals, and provide tailored recommendations to help you make the most of your money – for you and your family.
The Government has launched a consultation on a new ‘First Time Buyer ISA’. This is in response to the average age of first-time buyers rising, and the current Lifetime ISA product having an upper age limit of 40 for new savers.
The new ISA will still include a 25% government bonus, but this will now be paid when scontracts are exchanged on your first home, rather than added each year.
Importantly, the previous 25% withdrawal penalty will be removed, meaning you won’t lose part of your original savings if you need to take the money out for another reason.
The new proposed product does appear to address some of the issues with its predecessor, but an important point of note is that the consultation has not yet addressed the £450,000 price cap.
This was originally set in 2017 when the Lifetime ISA was launched, with the Government stating that the limit ensures the support goes to those that need it most.
We will be watching the consultation closely for further developments.
If you have any questions on your savings and investments, please get in touch with one of our advisers.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
| Match me to an adviser | Subscribe to receive updates |
The Government plans to introduce a 22% charge on interest earned from cash held within non-cash ISAs, such as Stocks & Shares ISAs and Innovative Finance ISAs, from April 2027.
Cash ISAs will continue to offer tax advantages, but annual allowance changes have been announced, with reduced limits for some savers.
The Government aims to encourage more people to invest rather than hold large amounts of cash in savings accounts, helping individuals potentially achieve higher long-term returns.
Inflation reduces the purchasing power of money over time. If savings growth does not keep pace with inflation, the real value of those savings falls.
The right approach depends on your goals, risk tolerance and time horizon. Professional financial advice can help determine the most suitable strategy for your circumstances.
The Government is consulting on a new First Time Buyer ISA, which would retain a 25% government bonus while removing the existing withdrawal penalty.
At present, the consultation has not proposed changes to the £450,000 property price cap, although this may be reviewed as the consultation progresses.
The annual Stocks and Shares ISA allowance is expected to remain at £20,000.
Where are you going on holiday this year?
As peak holiday season hoves into view, many of us will be thinking of distant shores, sun-drenched beaches and relaxing by the pool with a cool drink in hand.
The chances are that capital gains tax considerations or mulling over the relative benefits of active versus passive investing may be rather further from your mind.
But should they be?
In my experience, holidays aren’t just about taking it easy and sampling the delights of the local cuisine – although I have to confess that I do enjoy both of those.
Being on holiday also allows you to free yourself of your day to day work and home concerns and give you the time to think about other things.
In my case, I find holidays are about the only time I get to think about life in a wider context – where I want to go, what I want to do and how I can go about achieving that.
It is actually a great time to consider your life plan – and a big part of that is your financial plan.
For example, you might be sat in your sun lounger thinking “I could get used to this a bit more often”.
If that’s the case, maybe it’s time to consider whether you’re putting away enough money for a retirement which allows for plenty of foreign travel.
Perhaps you’re loving life so much that you may even be thinking about retiring abroad – in which case, what do you need to do to put that idea into motion and how early can you stop work to make your dream come true?
If you’re in the middle of a fun-filled family holiday, that might make you think a bit more about how you can help your children or grandchildren get a great start to their grown-up lives with savings put aside, or further down the road, begin their own pensions so they have financial security later in life.
Holidays also give you time to be nice to yourself and to spend money on doing things which you enjoy.
This should act as a reminder to you that saving money for retirement and accumulating wealth is a means to an end, not an end in itself.
The phrase “don’t be too busy making a living to make a life” is very apt here.
It is not uncommon in our profession to see clients who have built up retirement income comfortably into seven figures yet who still feel stressed and anxious about their finances.
They have enough assets to live a very comfortable and enjoyable retirement, but they are so used to saving money that they can’t permit themselves to spend it – they have built a fortress of wealth but somehow can’t bring themselves to live in it.
That’s another reason why talking to a financial adviser can be so beneficial.
As well as putting into action those plans you’ve mapped out while enjoying your sunshine break, a financial adviser can also act as an impartial expert observer of where your wealth actually stands.
Using impactful tools such as cashflow modelling and their own experienced insight, they can show you what’s possible with the money you’ve put aside.
So if you’re still wondering whether you can really afford that holiday of a lifetime you’ve always promised yourself, if the circumstances are right and the numbers add up, your adviser can give you the good news.
That could be something to really think about as you sip your sangria this summer.
For expert professional help on putting your financial goals into practice, get in touch with one of our advisers.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
How much do you value your time?
This is not a philosophical question, but a practical one.
I find it especially useful to think in these terms when I’m considering how and what to spend my time on.
It’s something all of us can do – and I’ll show you how.
First of all, think about how much you earn at work.
Some people are paid hourly, many people charge hourly rates for their work while others of us can work out our effective hourly rate by dividing a month’s salary by the number of hours worked.
Once you’ve got that figure, then consider how much you would charge or would want to be paid for working outside your normal hours – in the evenings, at weekends, or on Bank Holidays, for example.
I’d imagine that ‘out of hours’ work figure is quite a bit more than your normal hourly rate.
That’s why it’s important to spend that time wisely, whether that’s with your family, your friends, relaxing or enjoying hobbies.
If you spend your time wisely, I’d imagine you’d also want to spend your money wisely too – particularly when it comes to investing that money for your family.
When time and money are of the essence, is it a good idea to spend both at once?
I ask the question because that is what DIY investing essentially consists of.
Investing can be hugely rewarding, but it is also hugely complicated with significant consequences if you get things wrong.
As we always say whenever we talk about investing, the value of your investments can go down as well as up and you may not get back the full amount that you invested.
As a DIY investor, you can buy any publicly traded share, fund or bond anywhere in the world with no checks and balances and, thanks to technology, you can trade at the touch of a button anywhere you want.
If you manage to swerve the siren voices of social media influencers peddling questionable crypto and get rich quick schemes, how do you choose what to invest in?
You’re going to have to spend a lot of time researching investments – and if you use the ‘out of hours’ calculation, that process alone could cost you a lot of money.
For example, which country should you invest in?
If it isn’t the UK, how will you factor in exchange rate fluctuations? What effect will such investments have on the tax you pay, here and potentially in another country?
If you’ve chosen a country, which sector or sectors have the best growth prospects within that country and which individual companies are the best performers within those sectors?
Let’s say you decide not to invest in individual companies and countries but in an investment fund.
Which one of the 16,000+ funds should you choose?
Can you be sure that a fund that’s performed well previously will do so now?
Have the market conditions changed since that fund did well?
Do you know whether the people who were in charge of the fund when it was successful are still there now or have moved on somewhere else?
Add up the ‘out of hours’ time you need to put in to find the answers to these and myriad other investing questions and you can see you’re basically doing a second job to invest some of the money you make from your main full-time job.
With raising a family and making a home a job in itself, you’ve now got three full-time jobs to fit into your 24 hours a day.
And what happens if you’ve invested a lot of your family assets, future wealth and your precious time in something which turns out to be disastrous?
Did you really know the risks before you put your money into an investment and did those risks match up with how you feel about the potential of losing money?
Behavioural economics tells us that people feel losses twice as strongly as they do equivalent gains – do you want to feel personally responsible for losing money for your family and financial future after you have spent so much time trying to get it right?
There is no such thing as a foolproof investment but there are certain things which can help when it comes to investing:
Experience.
Expertise.
Knowledge.
Access to market and company intelligence and analysis.
Extensive support and guidance.
Constant research and updates.
This is what you get when you spend some of the money you have earned on bringing in an expert professional financial adviser like those at Fairstone.
While you deal on a one-to-one basis with your adviser so that he or she can really get to know you and understand your financial goals, in reality at Fairstone there is a whole team of people behind that adviser.
From researchers to paraplanners, portfolio managers to investment analysts, your adviser can call on a whole host of fully qualified experts to assist you.
In fact, what you have is essentially an “always on” adviser to help you negotiate not just the investment world but also assist in areas such as retirement planning, estate planning and financial protection, all while keeping an eye on important aspects of wealth building such as taxation.
And guess what?
All of this means you don’t have to get that ‘second job’ as a DIY investor – instead you can concentrate on the job which earns you money and the job of raising your family and making a home.
And as for that ‘out of hours’ time, you can spend it doing something you really love – rather than something you have to do.
That’s surely worth a lot, not just to you but also to your family and friends.
For expert professional help with your financial future, get in touch with one of our advisers.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Tax treatment depends on individual circumstances and may change. The value of investments can go down as well as up and you may not get back the full amount you invested. Past performance is also not a reliable indicator of future performance. Always seek professional advice before making financial decisions.
